
Personal Loan Interest Rates in India (2026): Average Rate, Bank vs NBFC Comparison
A personal loan is an unsecured loan provided by banks and NBFCs for any personal use—medical emergencies, weddings, vacations, debt consolidation, or business needs—without requiring collateral or security.
Key Characteristics (2026)
- Interest Rates: 9.15% - 24% p.a.
- Tenure: 1 to 5 years (12-60 months).
- Processing: 24-72 hours (Instant available).
- Collateral: None required (Unsecured).
| Credit Score Band | Typical Rate Range | Best Lender Type | Expected Approval Speed |
|---|---|---|---|
| 750+ | ~10.5% – 13.5% | Top Banks / Prime NBFCs | 24–72 hours |
| 700–749 | ~12.5% – 16.5% | Banks + Large NBFCs | 2–5 days |
| 650–699 | ~15% – 20% | NBFC-focused | 3–7 days |
| <650 | ~18% – 24%+ | Limited / Risk-based | Varies, stricter checks |
Ranges are indicative and vary by lender policy, income stability, FOIR, and city profile.
Average Personal Loan Interest Rate in India (2026)
Across the 21 banks and NBFCs Fincado tracks, the average starting personal loan interest rate is 9.96% p.a. Starting rates run from 9.15% to 11.10%, with a median of 9.99%. These are indicative starting rates as of 11 September 2026. The rate you are actually offered depends on your credit score, income and employer, and for many borrowers it is well above the starting rate.
- 9.96%
- Average starting rate
- 9.99%
- Median starting rate
- 9.15%
- Lowest starting rate
- 11.10%
- Highest starting rate
| Lender | Starting rate (p.a.) | Versus average |
|---|---|---|
| Canara Bank | 9.15% | 0.81 pts below |
| Bank of Maharashtra | 9.20% | 0.76 pts below |
| Union Bank of India | 9.25% | 0.71 pts below |
| Bank of India | 9.25% | 0.71 pts below |
| Central Bank of India | 9.25% | 0.71 pts below |
| Indian Bank | 9.40% | 0.56 pts below |
| LIC Housing | 9.45% | 0.51 pts below |
| Federal Bank | 9.50% | 0.46 pts below |
| Punjab National Bank | 9.55% | 0.41 pts below |
| Bank of Baroda | 9.65% | 0.31 pts below |
| HDFC Bank | 9.99% | 0.03 pts above |
| IDFC First Bank | 9.99% | 0.03 pts above |
| SBI | 10.00% | 0.04 pts above |
| ICICI Bank | 10.45% | 0.49 pts above |
| Bajaj Finserv | 10.49% | 0.53 pts above |
| Kotak Mahindra | 10.50% | 0.54 pts above |
| Tata Capital | 10.55% | 0.59 pts above |
| IndusInd Bank | 10.60% | 0.64 pts above |
| Aditya Birla Capital | 10.85% | 0.89 pts above |
| Axis Bank | 10.99% | 1.03 pts above |
| Yes Bank | 11.10% | 1.14 pts above |
Indicative starting rates compiled by Fincado, last updated 11 September 2026. Confirm the current rate with the lender before applying.
Current Interest Rates (2026)
Interest rates vary significantly based on lender type. Here is the landscape for October 2026.
Top Banks
| Bank | Rate Range | Processing Fee |
|---|---|---|
| SBI | 11.15% - 15.00% | 1.5% |
| HDFC Bank | 10.50% - 24.00% | Up to 2.5% |
| ICICI Bank | 10.75% - 19.00% | Up to 2.25% |
| Axis Bank | 10.99% - 21.00% | Up to 2% |
Top NBFCs
| NBFC | Rate Range | Processing Fee |
|---|---|---|
| Bajaj Finserv | 11.00% - 28.00% | Up to 3.93% |
| Tata Capital | 10.99% - 27.00% | Up to 2.75% |
| Aditya Birla | 11.50% - 24.00% | Up to 3% |
Credit Score Impact
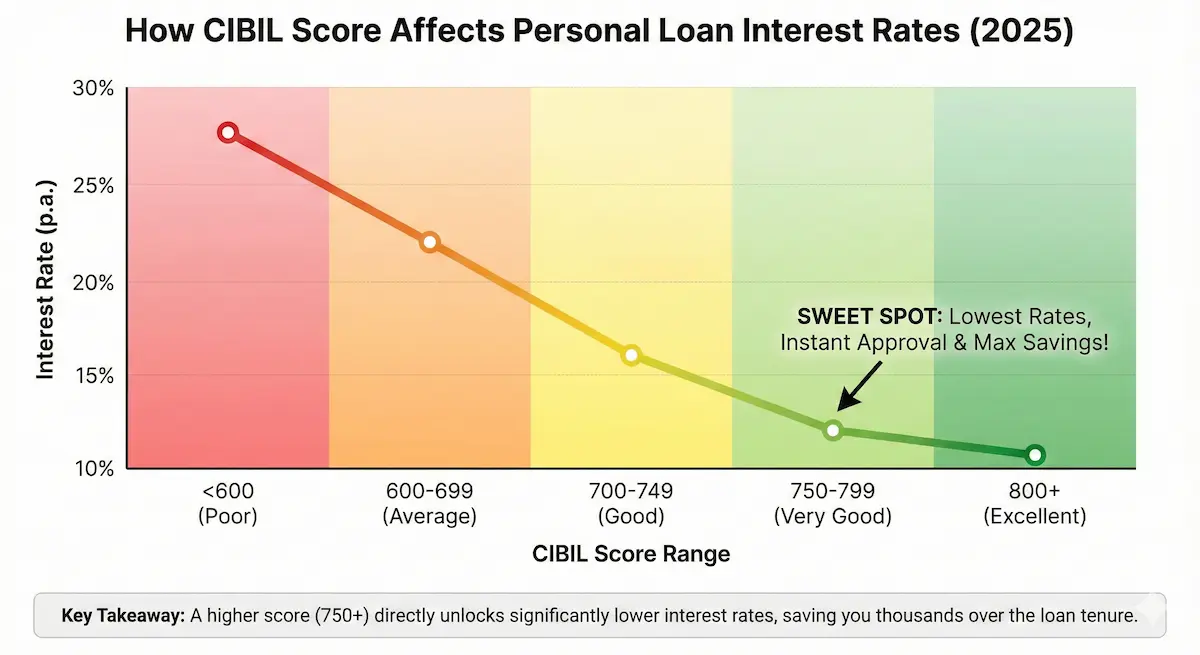
| CIBIL Score | Rate Impact | Approval Chance |
|---|---|---|
| 800-900 | Best (-3% discount) | 95%+ |
| 750-799 | Prime (-2% discount) | 90% |
| 650-699 | Higher (+2-3% premium) | 50% |
| < 600 | Max rates | 10-15% |
Scenario: Borrower with 650 CIBIL vs 800 CIBIL.
Rate Difference: 24% vs 11%.
Salary vs Self-Employed Rates
Self-employed borrowers typically pay 2-4% higher ratesdue to income variability.
| Lender | Salaried Rate | Self-Employed Rate |
|---|---|---|
| PSU Banks | 11.4% - 15.5% | 13.5% - 17.8% |
| Private Banks | 10.5% - 19% | 12.5% - 22% |
| NBFCs | 11% - 24% | 13% - 28% |
The "Flat Rate" Trap
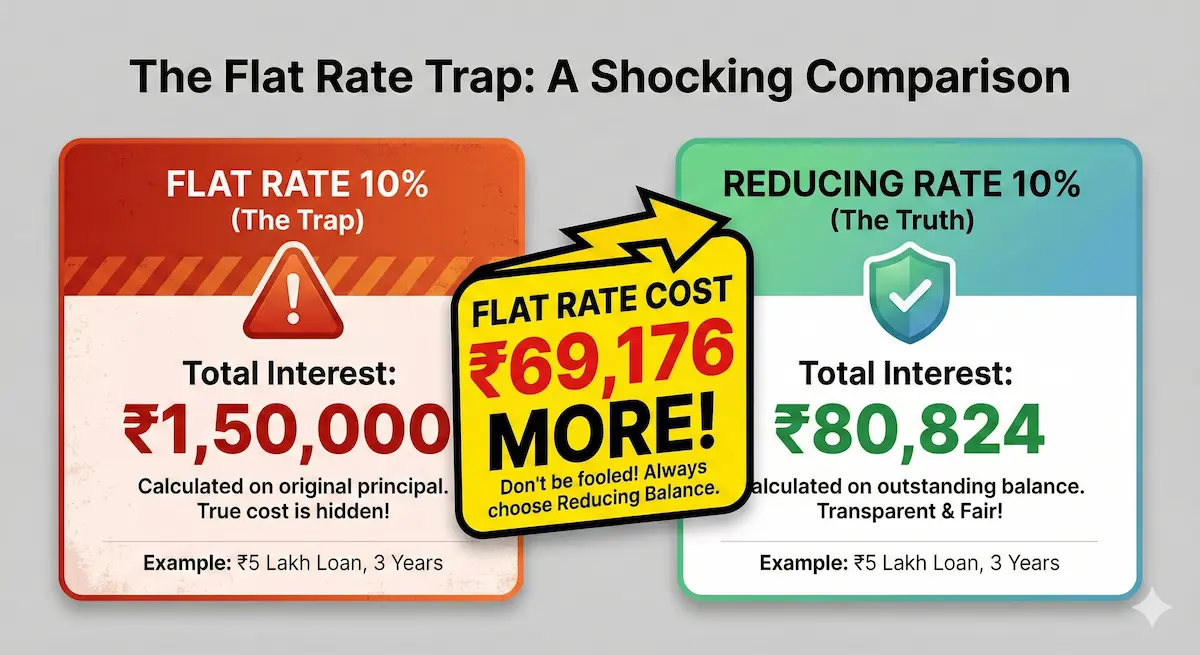
Dealer: "10% Flat Rate"
You pay interest on the full principal for the entire tenure, even as you repay.
Effective: ~18% Reducing
A 10% Flat Rate is actually equal to an ~18% Reducing Rate. You pay double!
EMI Comparison Table (₹5 Lakh)
| Rate | 1 Year EMI | 3 Years EMI | 5 Years EMI |
|---|---|---|---|
| 11% | ₹43,974 | ₹16,350 | ₹10,867 |
| 14% | ₹44,532 | ₹17,108 | ₹11,654 |
| 17% | ₹45,095 | ₹17,881 | ₹12,472 |
| 20% | ₹45,661 | ₹18,670 | ₹13,320 |
| 24% | ₹46,420 | ₹19,745 | ₹14,497 |
Negotiation Playbook
- Know Leverage: CIBIL 750+ & Stable Job = High Leverage.
- Get Multiple Offers: Apply to 3-4 lenders within 15 days.
- Leverage Relationship: “I've been banking with you for 5 years."
- Compete: “HDFC offers 12.5%. Can you beat it?"
- Fees: Negotiate processing fee caps.
Prepayment & Foreclosure
Personal loans often have penalties.
| Lender | Lock-in | Penalty |
|---|---|---|
| SBI | 6 months | 3% |
| HDFC | 12 months | 2-4% |
| ICICI | 6 months | 4-5% |
When NOT to Take a Personal Loan
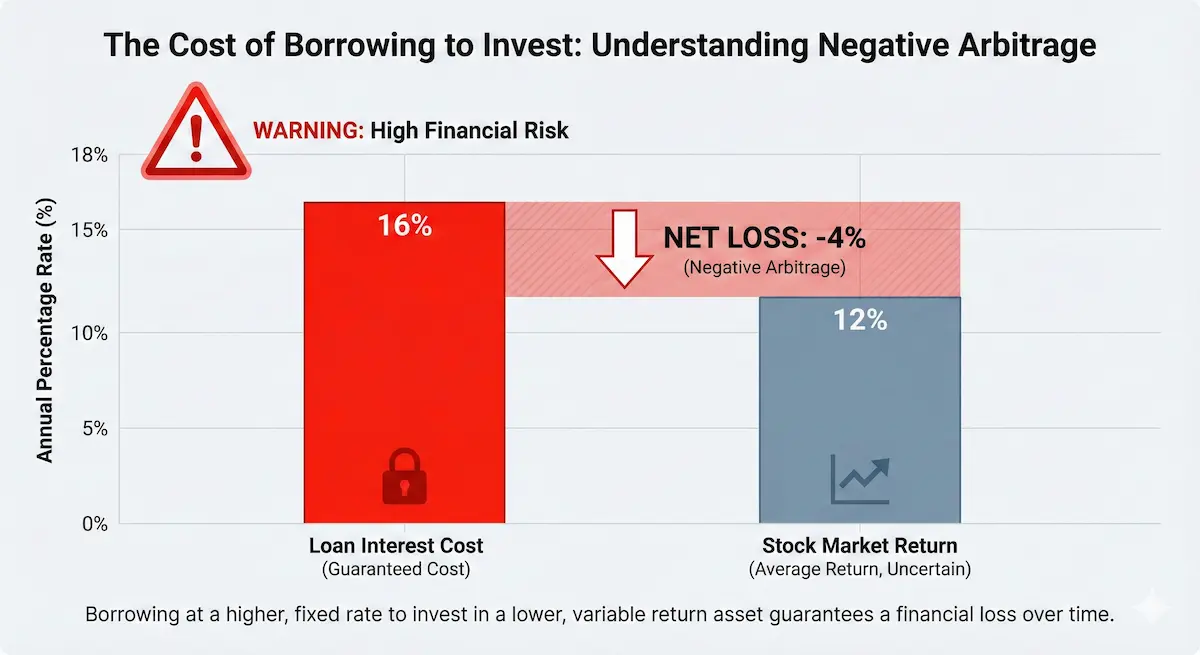
1) Discovery stage: find the right lender band
2) Validation stage: check EMI + profile readiness
3) Decision stage: reduce borrowing cost before applying
Frequently Asked Questions (FAQs)
Final Verdict
A Personal Loan is a great tool for emergencies, but a bad habit for lifestyle expenses.
Nitin researches and writes all financial guides on Fincado, cross-checking figures against RBI circulars, official bank disclosures, and the Income Tax Act. Content on this site is independent analysis — not personalized financial advice.
Oct 2026
Source cross-check and periodic QA
Actual outcomes can vary by borrower profile, bank policy, market conditions, and future rule changes. Validate important decisions with a certified professional.
Disclaimer: Interest rates and terms are subject to change by lenders. This guide is for educational purposes. Please check the loan agreement carefully before signing.